Insure your property with Skydd
Get the right protection for your rental property without spending more than necessary
Insure your property with Skydd
Get the right protection for your rental property without spending more than necessary
Legally required
NIIRA Section 76 makes property insurance compulsory for all buildings occupied by tenants.
Built for rental properties
Coverage designed for landlords, not homeowners. Includes loss of rent, tenant liability, and building damage.
Fast and digital
Get a quote in minutes. No broker visits. No paper applications. No phone calls.
What landlord insurance covers
Building and structure
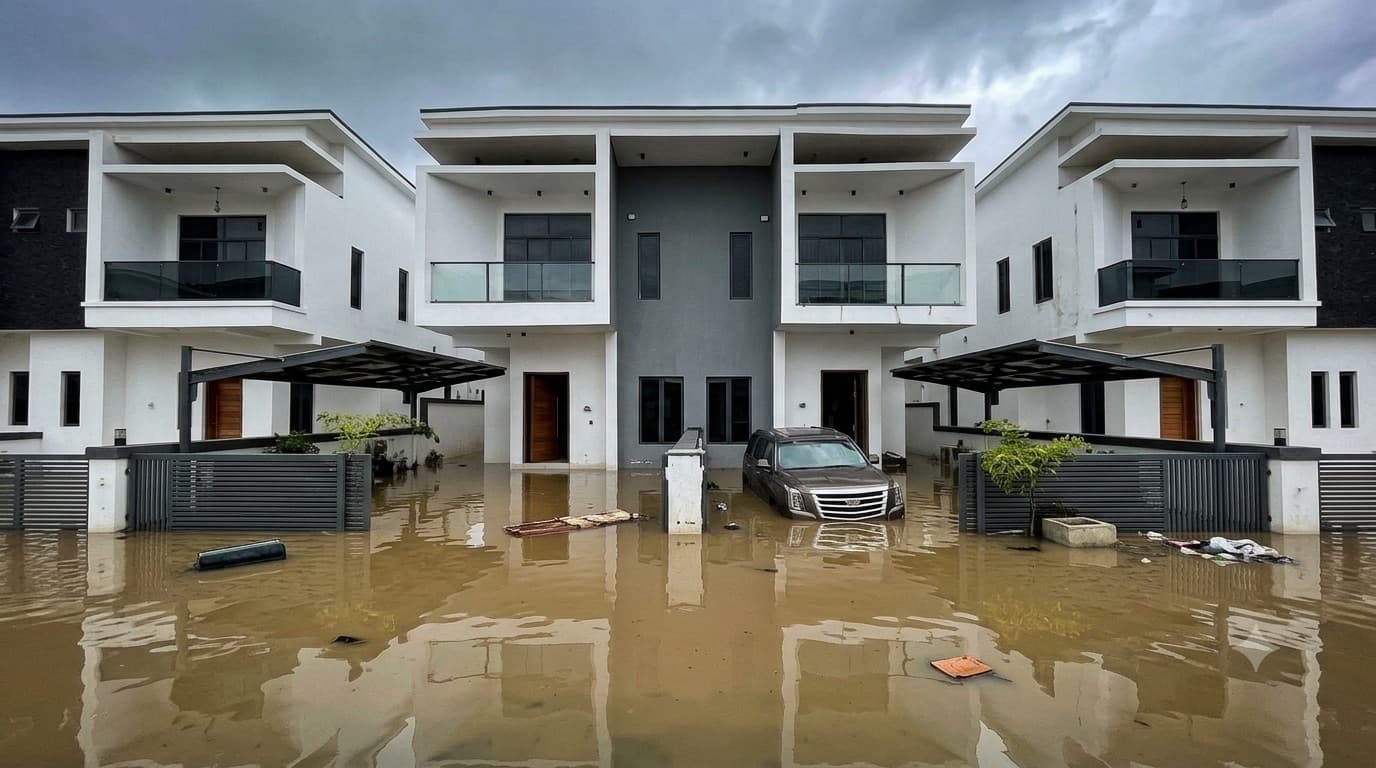
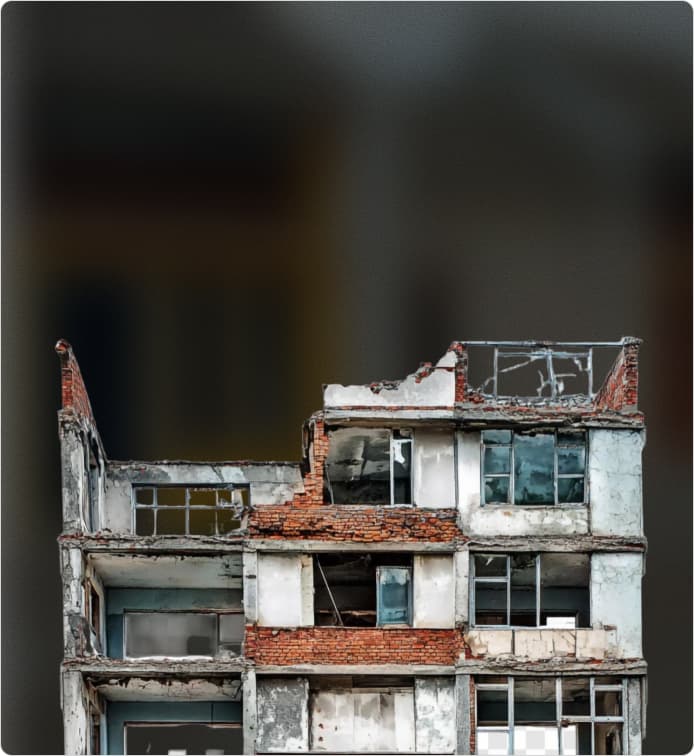
Fire. Flood. Collapse. Earthquake. Storm. The building itself is covered against the hazards specified under NIIRA. Structural damage that would otherwise wipe out years of rental income is insured.
Loss of rent
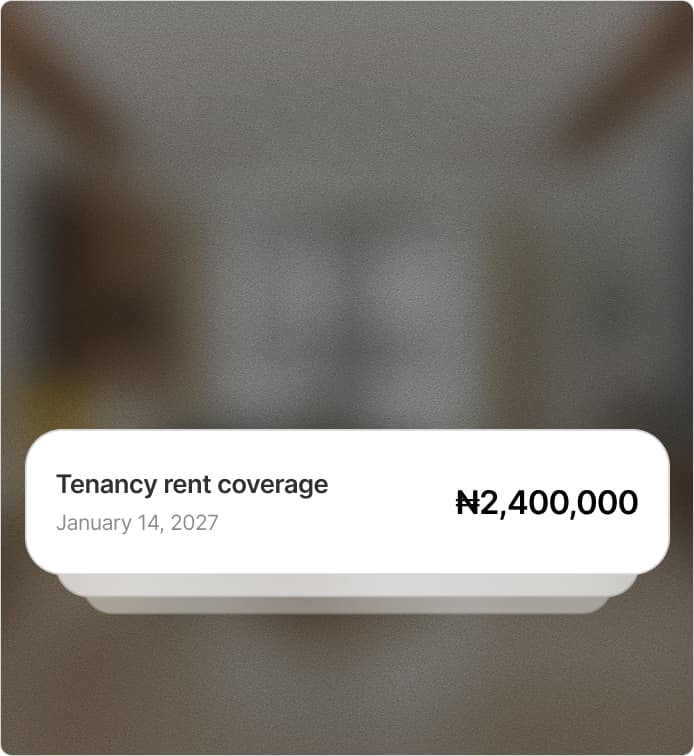
When damage makes a property uninhabitable, rental income stops. Loss-of-rent coverage replaces that income while repairs are completed. The property earns even when tenants cannot occupy it.
Injury on the property
NIIRA requires coverage for the legal liabilities of the owner and occupier — bodily injury or death suffered by tenants, visitors, or third parties on the property.
Burglary
Theft and damage from a break-in — forced entry, and the fixtures and fittings taken or wrecked on the way out. Covers making the property secure and habitable again.
Why landlords are insuring their investment
| Feature | Uninsured | Roofteller |
|---|---|---|
| NIIRA compliance | ||
| Fire and flood coverage | ||
| Loss of rent protection | ||
| Injury on the property (tenants and third parties) | ||
| Burglary and theft coverage | ||
| Digital claims process | ||
| Linked to property banking account | ||
| Penalty risk covered: ₦1M fine or 12 months |
Frequently asked questions
Yes. Section 76 of the Nigerian Insurance Industry Reform Act (NIIRA) makes insurance compulsory for every building occupied by tenants. Non-compliance carries a fine of at least ₦1,000,000, imprisonment for up to 12 months, or both.
It protects the building and your rental income against the hazards specified under NIIRA — fire, flood, collapse, storm, and earthquake — plus liability for injury or death suffered by tenants, visitors, and third parties on the property, loss of rent while damage is repaired, and theft or damage from a break-in.
Homeowners policies assume the owner lives in the property and exclude tenant-related risks. Landlord insurance is built for rented buildings — it covers loss of rent, liability for injury on the property, and burglary that a standard homeowners policy leaves out.
Premiums depend on the building's value, location, and construction type. Because everything is digital, you get an accurate quote in minutes rather than waiting on a broker. Coverage for a single unit typically costs a fraction of one year's rent.
Policies are underwritten by NAICOM-licensed insurers. Roofteller handles quoting, payment, and claims in one place, so you deal with a single digital dashboard instead of chasing brokers and paperwork.
Yes. You can insure every property in your portfolio from one account, each building quoted and documented separately, with a single view of what is covered and when each policy renews.
Claims are filed digitally from your dashboard — no branch visits. You upload evidence of the damage, and payouts, including loss-of-rent settlements, are paid into your Roofteller property account so the money lands where your rent is already managed.
No. A caution fee is a small refundable amount held against minor tenant damage. It cannot cover fire, flood, collapse, liability claims, or lost rent — and it does not satisfy the NIIRA requirement. Insurance is a separate legal obligation.
Protect your investment
Fire, flood, collapse, liability, and loss of rent.